If you've read anything about paying off debt, you've met the argument. Avalanche people say pay the highest interest rate first, because maths. Snowball people say pay the smallest balance first, because motivation. Both sides have a point, and both sides tend to skip the part that matters most.
That part is the cascade: what happens to a debt's payment after the debt is gone. Get that right and either order works. Get it wrong and neither does.
The three ideas, briefly
Avalanche. Pay the minimum on everything, and put every spare dollar on the debt with the highest APR. When it's gone, move to the next highest.
Snowball. Pay the minimum on everything, and put every spare dollar on the smallest balance. When it's gone, move to the next smallest.
Cascade. When any debt is paid off, its whole payment rolls onto the next target instead of leaving the debt budget. This isn't a rival to the other two. It's the engine underneath both of them, and the step people most often skip in real life.
A worked example
A made-up household with three debts. We'll assume no new charges, rates that don't change, and fixed minimum payments, which keeps the arithmetic honest and the comparison fair. Real cards recalculate minimums as balances fall, so treat these as illustrations, not forecasts.
| Debt | Balance | APR | Minimum |
|---|---|---|---|
| Card A | $6,000 | 24% | $180 |
| Card B | $1,500 | 18% | $50 |
| Personal loan | $3,500 | 11% | $160 |
| Total | $11,000 | $390 |
First: no extra money at all
Say they can only afford the $390 in minimums. Compare two habits.
| All debts gone | Total interest | |
|---|---|---|
| Minimums only; each freed payment gets spent | about 56 months | about $4,920 |
| Same $390, freed payments roll forward (cascade) | about 39 months | about $4,120 |
Same budget. Not one extra dollar. Seventeen months sooner and roughly $800 less interest, purely because when the loan ended in month 25, its $160 kept working instead of quietly turning into spending.
In this version, the order barely matters: avalanche and snowball finish in the same month, about $25 apart. The cascade did the heavy lifting.
Then: $300 extra a month
Now say they find $300 a month on top of the minimums, for $690 in total.
| First debt gone | All debts gone | Total interest | |
|---|---|---|---|
| Avalanche (Card A first) | month 15 | month 19 | about $1,670 |
| Snowball (Card B first) | month 5 | month 19 | about $1,990 |
Both rely on the cascade. Here the order does matter. Avalanche saves about $315, because the expensive 24% balance gets attacked from day one instead of waiting its turn. Snowball gets its first win ten months sooner, and that's not nothing: month 5 is a lot closer than month 15 when you're tired of all this.
So which one?
Honest answer: the one you'll stick with, as long as the cascade is in it.
Lean avalanche if: the rates are far apart, one balance is large and expensive, and you're the kind of person who's motivated by the total interest going down. It's always the cheaper order on paper.
Lean snowball if: you have several small debts and you need to feel progress to keep going. If an early win is the difference between sticking with it and giving up in month four, the extra interest is a reasonable price.
A middle path: if one debt is tiny and would be gone in a month or two, clear it first for the win, then go avalanche on the rest. You'll pay a little more interest than pure avalanche, usually not much.
What doesn't work is no plan at all, where extra money goes wherever it feels urgent this month and freed payments drift into everyday spending.
Where 0% fits
Interest-free plans go last in any order, whatever their balance. Paying them early saves nothing. Snowball fans sometimes put a small 0% plan first because it's the smallest balance. Don't: the win isn't worth the extra interest you keep paying on the debts that charge it. The exception is a deferred-interest promotion, which needs to be cleared by its deadline, but that's a matter of setting money aside in time, not paying early.
Making the cascade happen
The cascade sounds automatic. It isn't. When a debt ends, your bank doesn't move its payment to the next debt for you. Someone has to:
- Notice. The last payment happens; the next month, nothing goes out.
- Decide. Which debt gets it? With an avalanche, that's the highest APR still open.
- Change the payment. Raise the target debt's automatic payment by the freed amount.
Miss step one and the money is absorbed before you notice. Skip step three and it's a good intention.
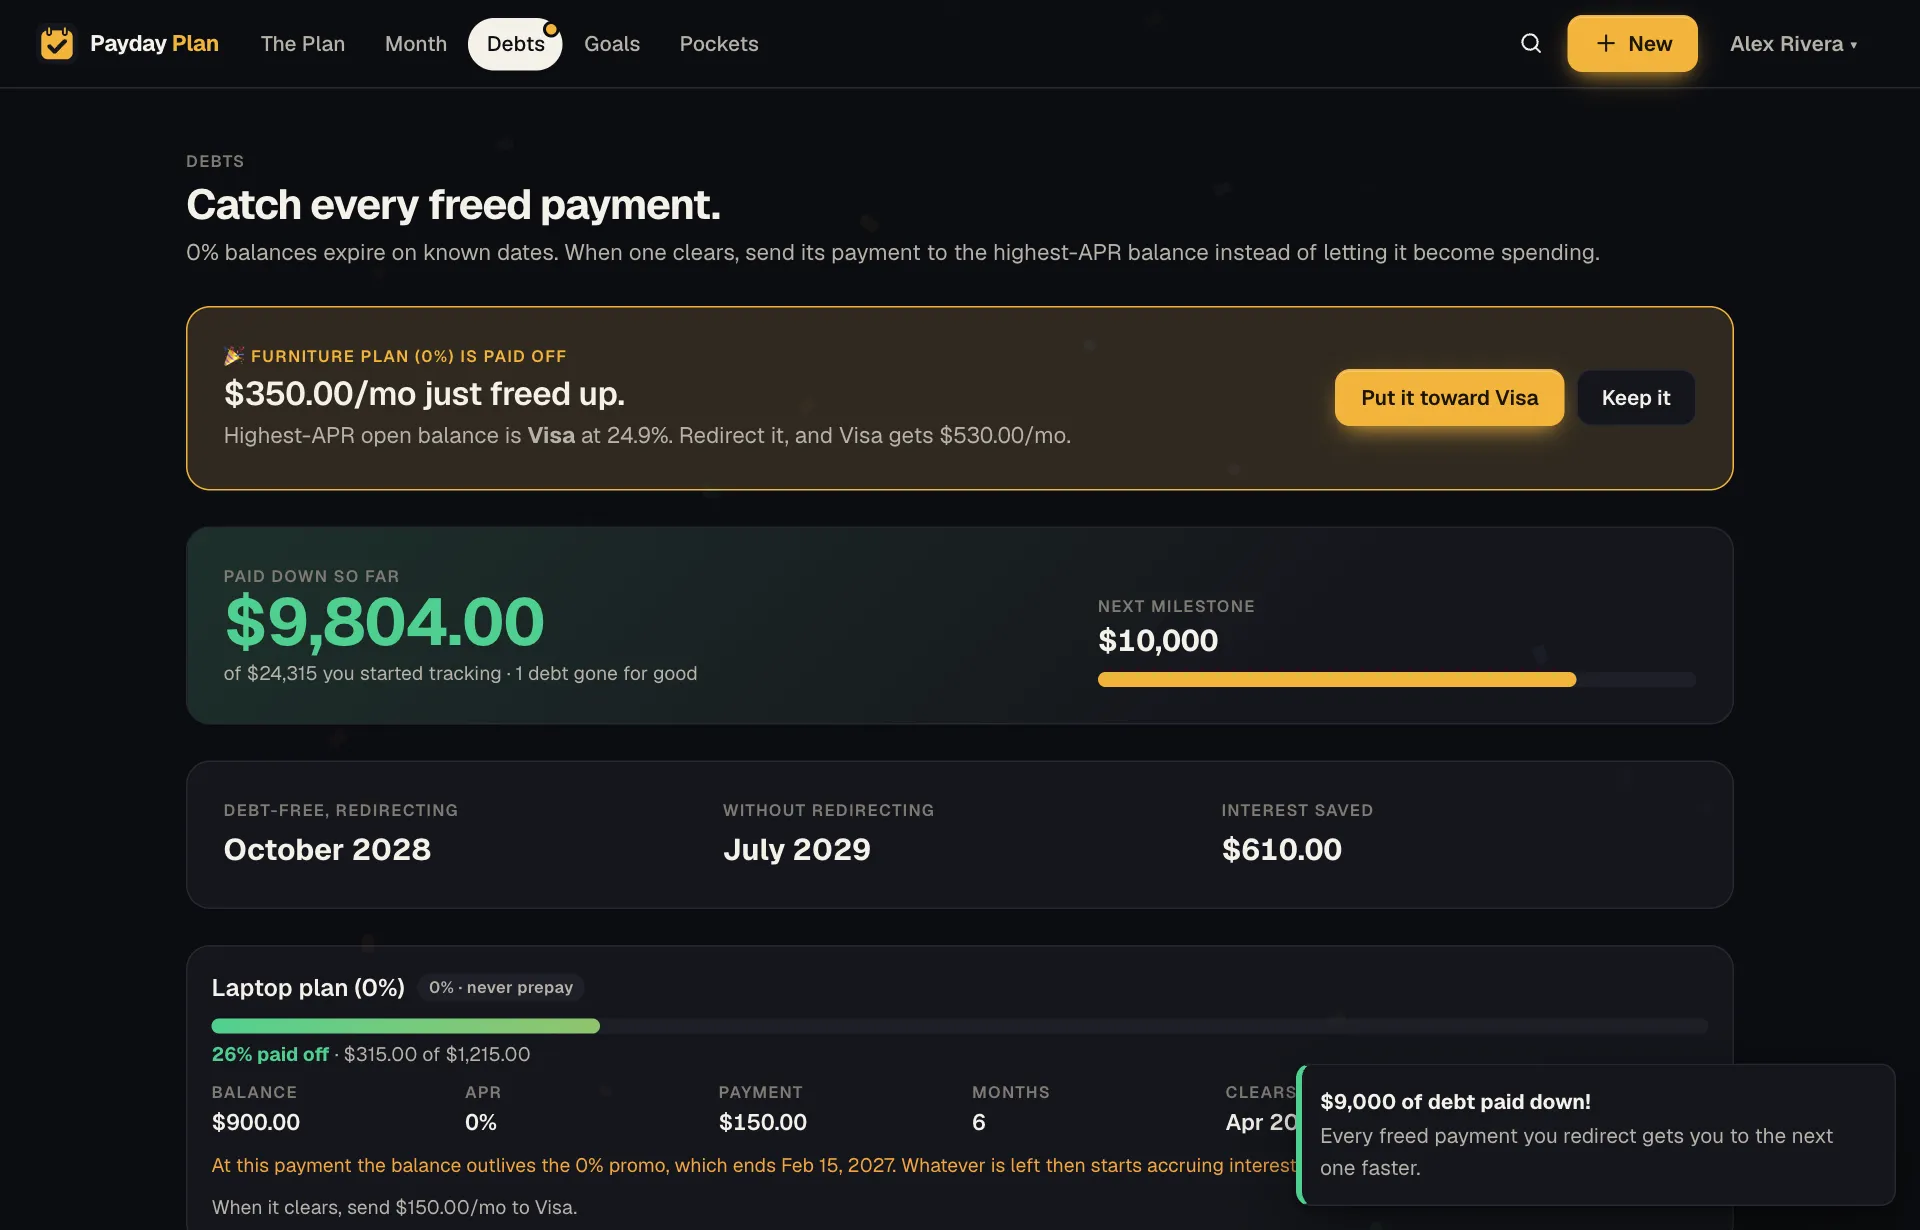
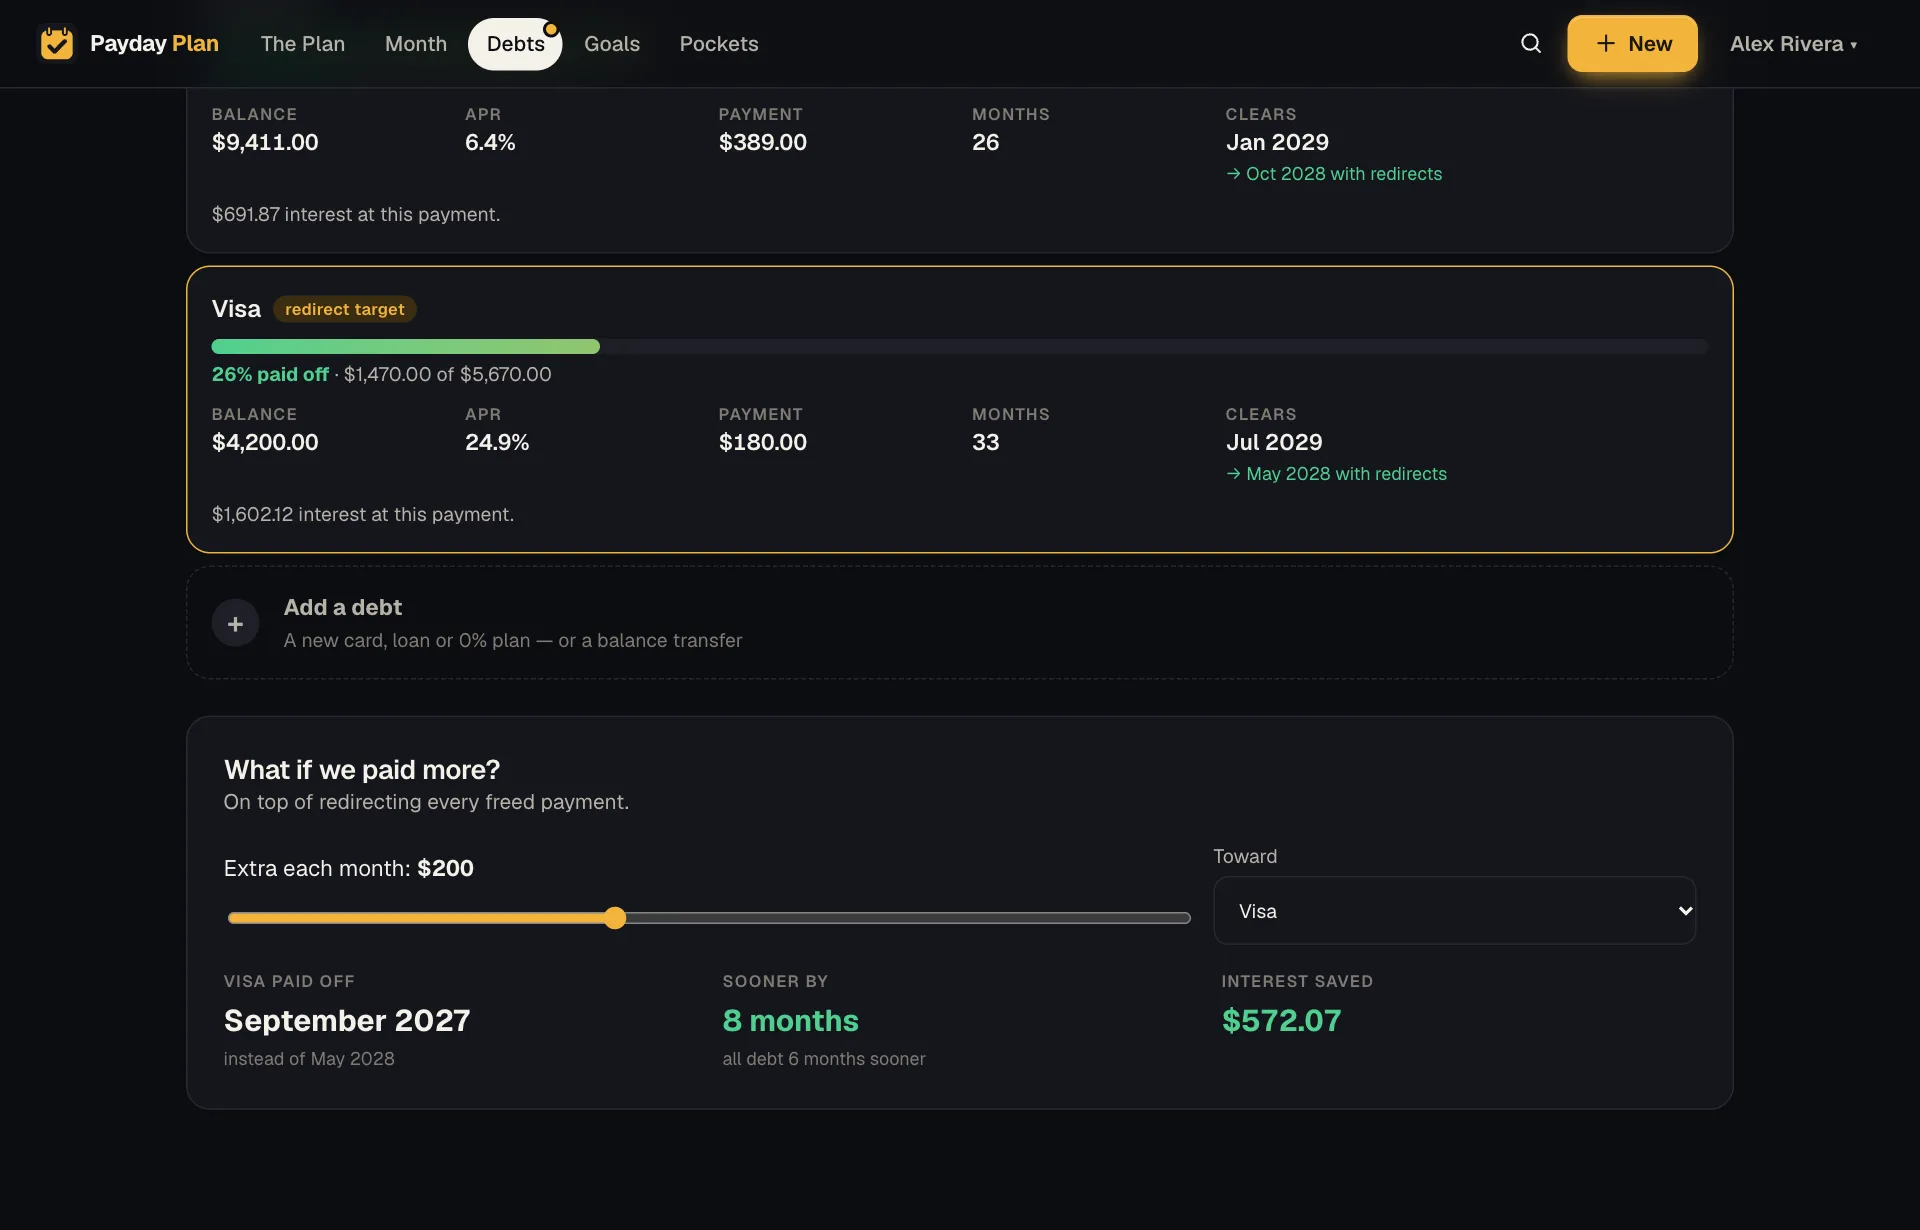
Try it: Payday Plan was built around this moment. When a debt reaches zero, its bill stops recurring and both of you see a prompt: redirect the freed payment to the highest-APR open debt with one click, which raises that debt's payment and its bill, or keep it. 0% debts are never offered as targets. The Debts page shows every debt's payoff month and a what-if slider for trying an extra amount first.
You can add each debt with a sentence:
Visa card $6,000 balance at 24%, paying $180 a month on the 14th