
Paying off a debt is a good day. It's also the day a few hundred dollars a month goes looking for a new job. Without a plan, it usually finds one at the drive-through.
Payday Plan's debt page is built around one idea: every freed payment gets a decision.
Every debt, and when it's done
Add each debt with its balance, interest rate (APR) and monthly payment. If it's on a 0% promotional rate, add the date the promo ends. You can link a debt to the bill that pays it, so ticking that bill takes the payment off the balance. (Un-tick it and the exact amount goes back.)
For each debt you'll see:
- The payoff month at the current payment.
- How much of it is paid off, as a percentage.
- Whether it ever clears. If a payment doesn't cover the interest, it says so plainly.
Interest-bearing debts are worked out month by month (interest first, then the payment), because dividing the balance by the payment makes a high-rate card look much closer to done than it is.
Paid down so far
At the top: how much you've paid down across every debt. Every time that total crosses another $1,000, there's a bit of confetti. It's a small thing. Small things help on a long road.
The freed-payment cascade
When a debt's balance reaches zero:
- The debt clears, and its bill stops recurring.
- A prompt appears for both of you, on The Plan and at the top of the Debts page: redirect the freed payment, or keep it?
- Click Put it toward (the button names your highest-rate open debt) and one click raises that debt's payment and its bill. Keep it leaves the money for you to place.
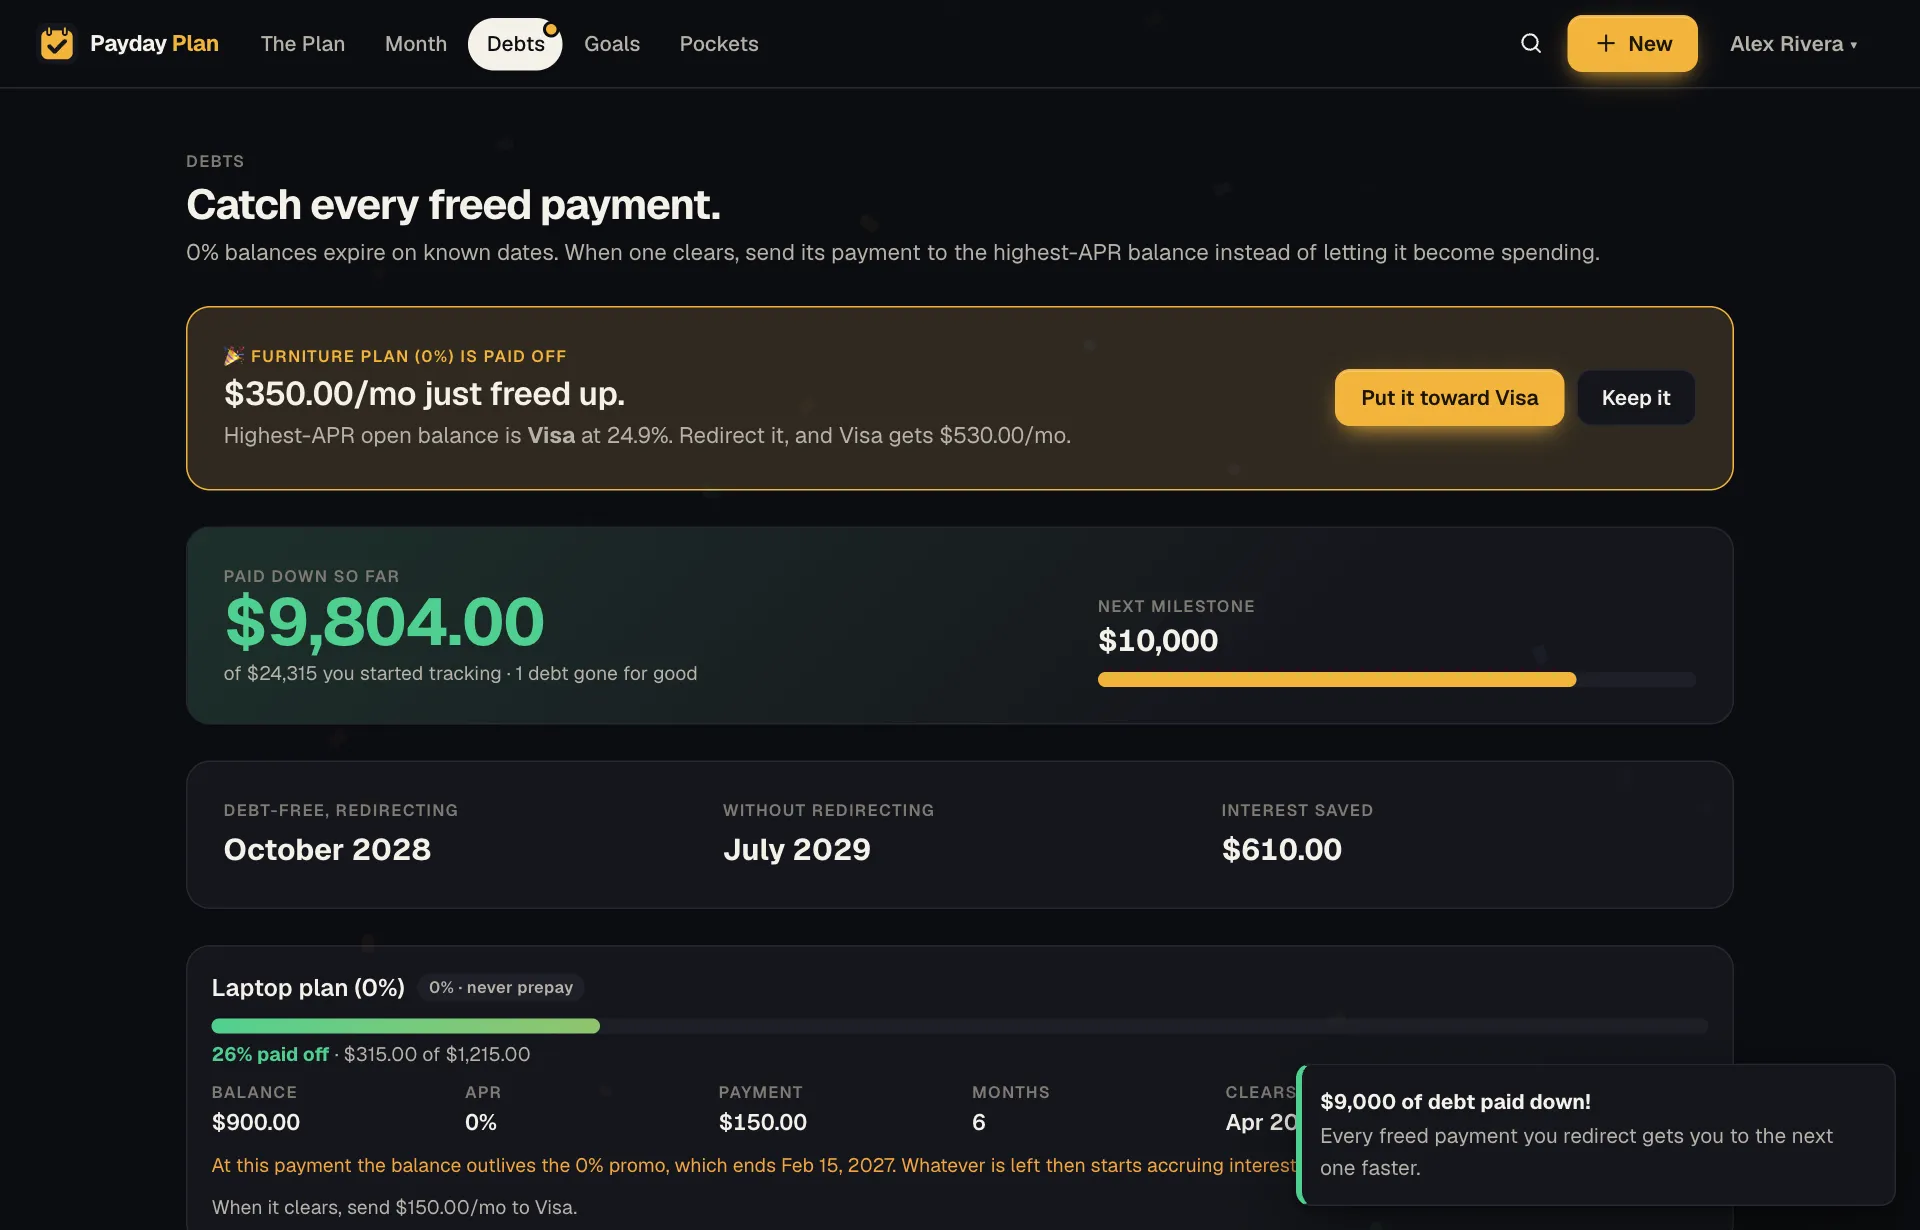
Say the car loan finishes and its $340 payment is freed. (Example figures.) Instead of that $340 drifting into the grocery pocket, it goes to the card at the highest APR, which then clears sooner, which frees a bigger payment for the next one. That's the cascade.
You can also see the whole runway both ways, near the top of the page: Debt-free, redirecting and Without redirecting, with the Interest saved between them.
Once every interest-bearing debt is gone, a freed payment goes to the savings goal that's furthest behind instead.
Never prepay a 0% plan
A 0% balance is never a redirect target. Paying ahead on interest-free money costs you the use of that money and saves nothing. If only 0% debts are left, the freed payment is simply yours to decide about.
What if?
The What if we paid more? panel at the bottom of the Debts page answers the question everyone asks:
$200 more to Chase — paid off when?
Drag Extra each month, pick the debt under Toward, and see the new payoff month next to the old one, how many months sooner, and the interest saved. Nothing changes until you actually change the payment.
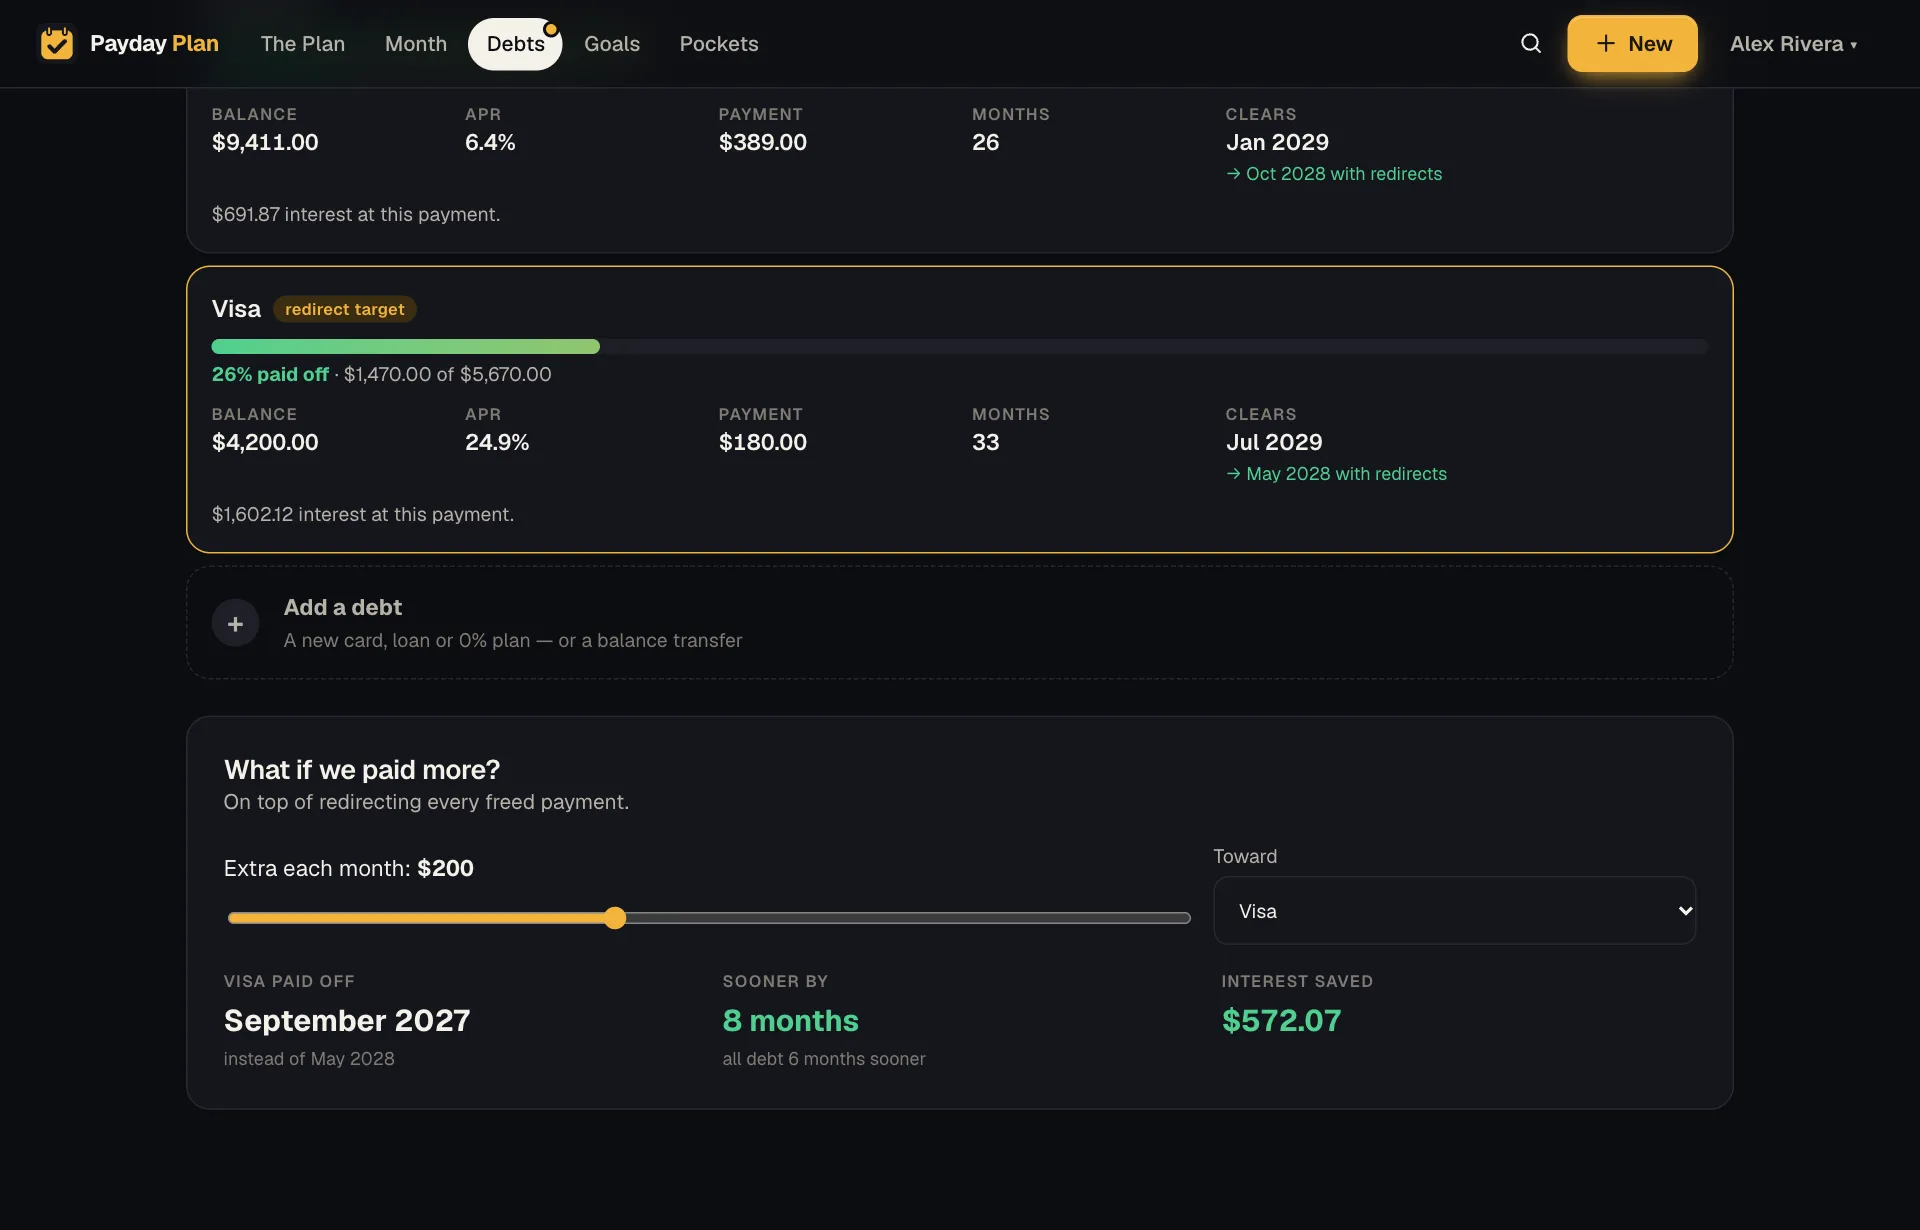
Try it: Set the slider to the amount you spend eating out in a typical month and see what it does to your highest-rate card. Then decide for yourself whether the burritos are worth it.
Promo endings, with fair warning
A 0% promotion that quietly reverts to 27% is an expensive surprise. Payday Plan emails both adults 60, 30 and 7 days before a promo ends. The debt page also warns if the balance is on track to outlive the promo at the current payment, while there's still time to do something about it.
What it isn't
Payday Plan does the arithmetic on the numbers you give it. It isn't financial advice, and it doesn't know your whole situation. The highest-rate-first order is a rule of thumb you can follow, change or ignore. What it makes sure of is that the choice is yours, not something that happened by default.