Couples rarely fight about the electric bill. They fight about whether it was paid. About the $140 that went somewhere neither of them remembers. About one person feeling like they carry all the money worry while the other one doesn't seem to think about it at all.
Those are fights about information, not values. Who knows what, who did what, and who's supposed to notice. Fix the information, and a surprising number of the arguments go away by themselves.
The default arrangement, and why it strains
In many households, one person ends up as the money person. They pay the bills, know the balances, notice the problems. The other is told when something's wrong.
It works, sort of. But it puts a constant low-level weight on one person, and leaves the other with no real picture, so every question sounds like an audit and every answer sounds defensive. If the money person is ill or away, nobody knows what's due.
The aim isn't for both of you to do everything. It's for both of you to be able to see everything, and to have agreed who does what.
Agree on four things
1. Who pays which bills
Split them by whatever's natural: whose name is on the account, who set it up, or just alternate. Write the split down. The point isn't fairness to the dollar. It's that every bill has exactly one person whose job it is.
2. How you know it's done
A bill isn't paid when someone means to pay it. It's paid when it's marked paid somewhere you can both see. That one habit removes most "did you pay the…?" conversations.
3. What needs a conversation
Pick a number. Any purchase over it gets a quick check with the other person first. $100, $200, whatever suits your income. Below it, no discussion required. This turns a vague sense of "we should talk about big things" into a clear line.
4. What's yours to spend, no questions
Each of you gets an amount of personal money per paycheck. It's equal or proportional, but either way it's genuinely yours, with no explaining. This is often the single most helpful thing a couple can add. It turns the coffees and the hobby supplies from shared-budget debates into nobody's business.
A worked example
A made-up household. One partner takes home $4,000 a month, the other $2,500. Shared costs (housing, bills, groceries, childcare, debt payments) come to $5,000.
There are two common ways to split this.
Proportional. Each pays the same share of their income toward shared costs.
| Take-home | Share | Toward shared costs | Left | |
|---|---|---|---|---|
| Partner 1 | $4,000 | 61.5% | $3,077 | $923 |
| Partner 2 | $2,500 | 38.5% | $1,923 | $577 |
| Total | $6,500 | $5,000 | $1,500 |
Fully pooled. Everything goes into one plan. From the $1,500 left over, they agree $600 goes to savings and each person gets $450 of personal money a month.
Neither is more correct. Proportional suits couples who want some financial independence. Pooled suits couples who think of it all as one household's money. What matters is that you choose, out loud, instead of drifting into an arrangement one of you resents.
Then the jobs:
| Job | Who |
|---|---|
| Rent, utilities, internet | Partner 1 |
| Childcare, phone, subscriptions | Partner 2 |
| Credit card payments | Partner 1 |
| Weekly look at the plan | Both, Sunday evening, ten minutes |
| Check before spending over $150 | Both |
| What happens to a freed payment | Both |
Make the plan the shared truth
Arguments get worse when each person is working from different numbers: one is looking at the bank app, the other remembers last month's total. Agree on one place where the plan lives, and treat it as the answer.
That place should show:
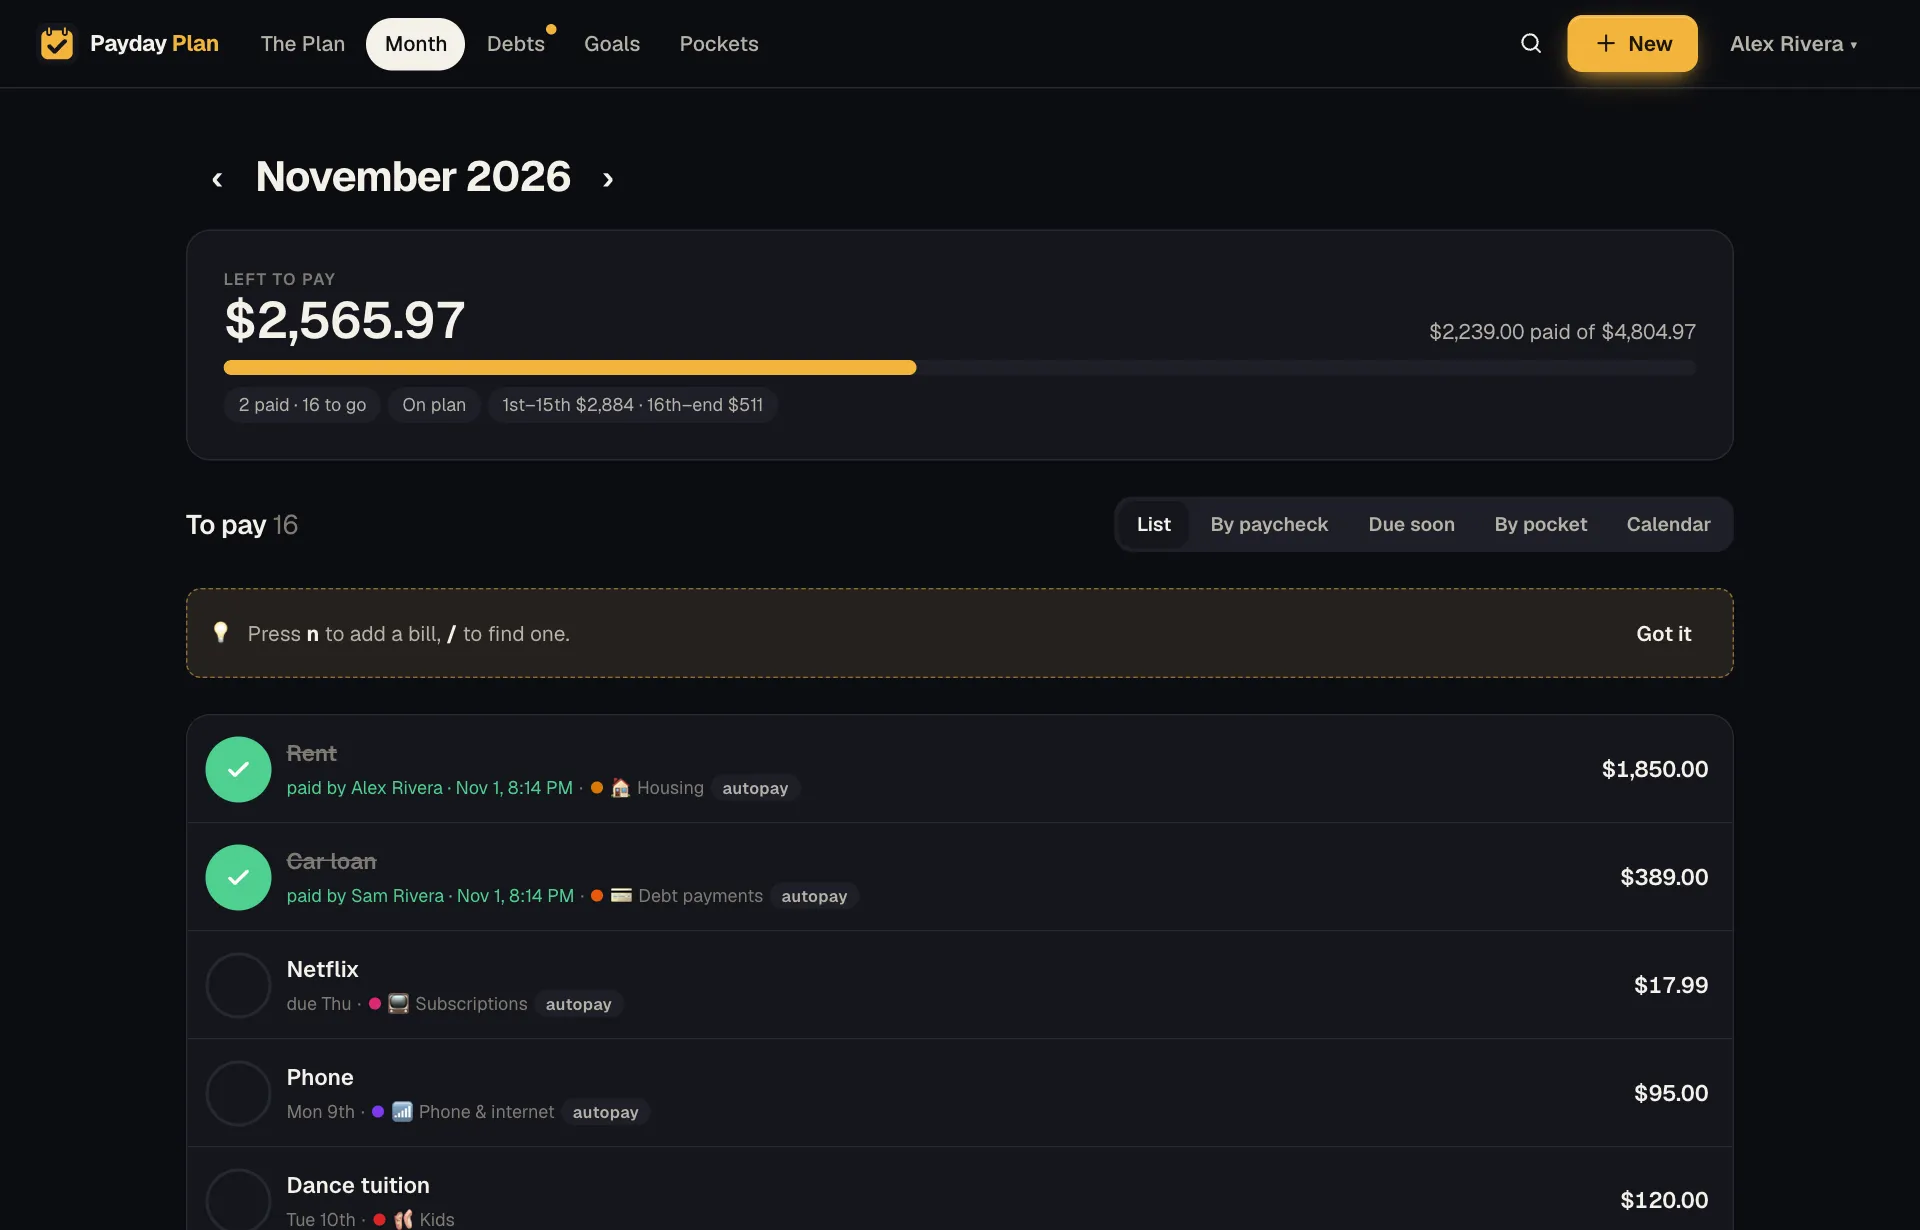
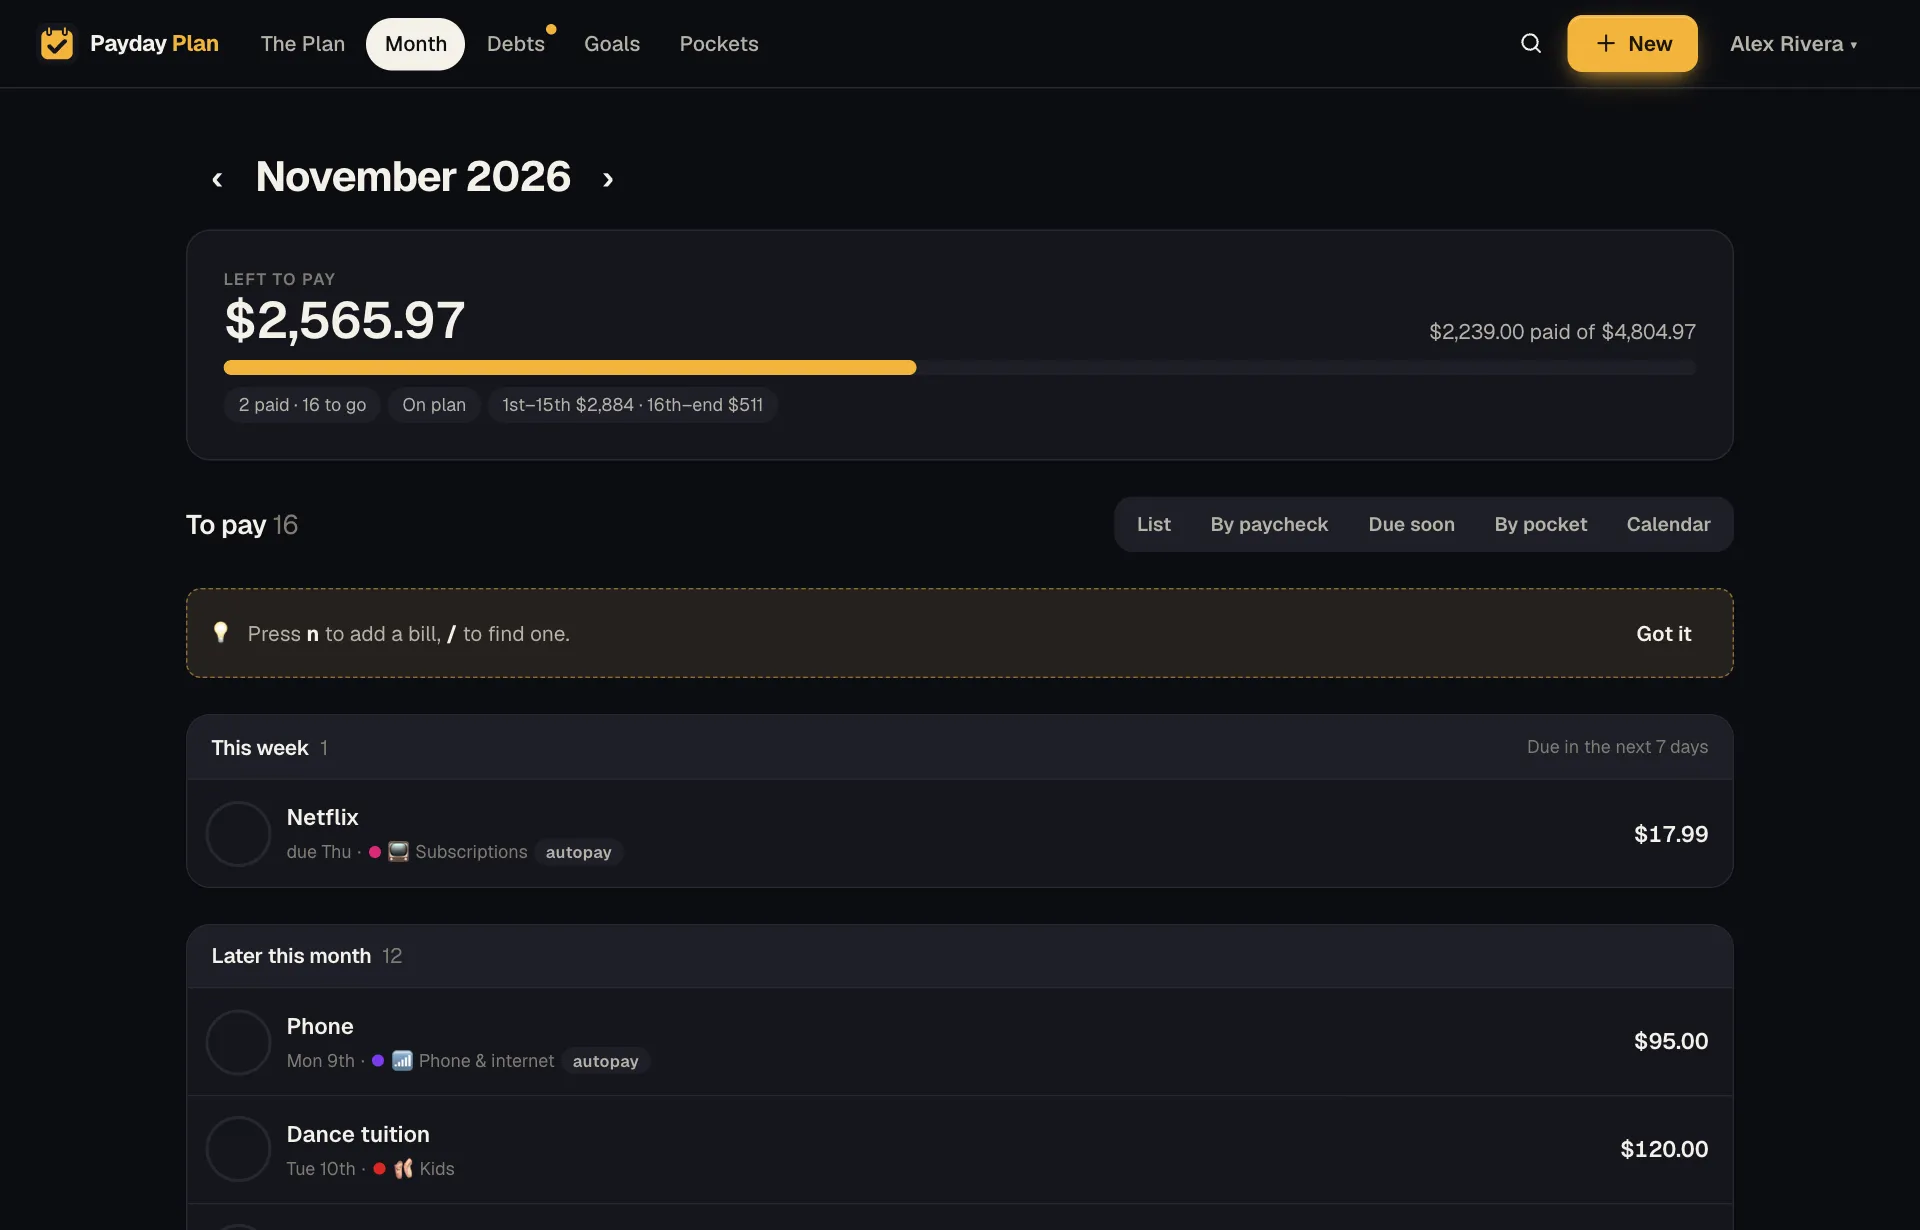
- Every bill, and whether it's paid this month.
- Who marked it paid. Not to keep score, but so the question "did you…?" has an answer you can look up.
- What's free to spend until the next payday.
- What's coming up in the next week.
A short weekly look together beats a long monthly reckoning. Ten minutes on a Sunday: what's due this week, anything that came in different, anything either of you is planning to buy. Done.
Decide the big moments together
Some decisions shouldn't be made by whoever happens to be looking. The month a debt is paid off is the clearest example: its payment is suddenly free, and the choice of where it goes is one of the largest money decisions you'll make all year. The end of a 0% promotion is another. So is changing a savings goal.
Agree that those are joint decisions, and that neither of you acts on them alone.