You check the account on a Thursday evening. It says $4,200. That feels like a lot. You book the restaurant.
But $1,900 of that is rent, due in eleven days. Another $1,100 is childcare. Some of it is next week's groceries. The $4,200 was true, it just wasn't yours.
Your balance answers "how much money is in here?" The question you actually have is "how much of this can I spend without breaking anything?" That's a different number, and most people never calculate it. They estimate it by feel, which works right up until it doesn't.
The definition
Here's a definition worth adopting:
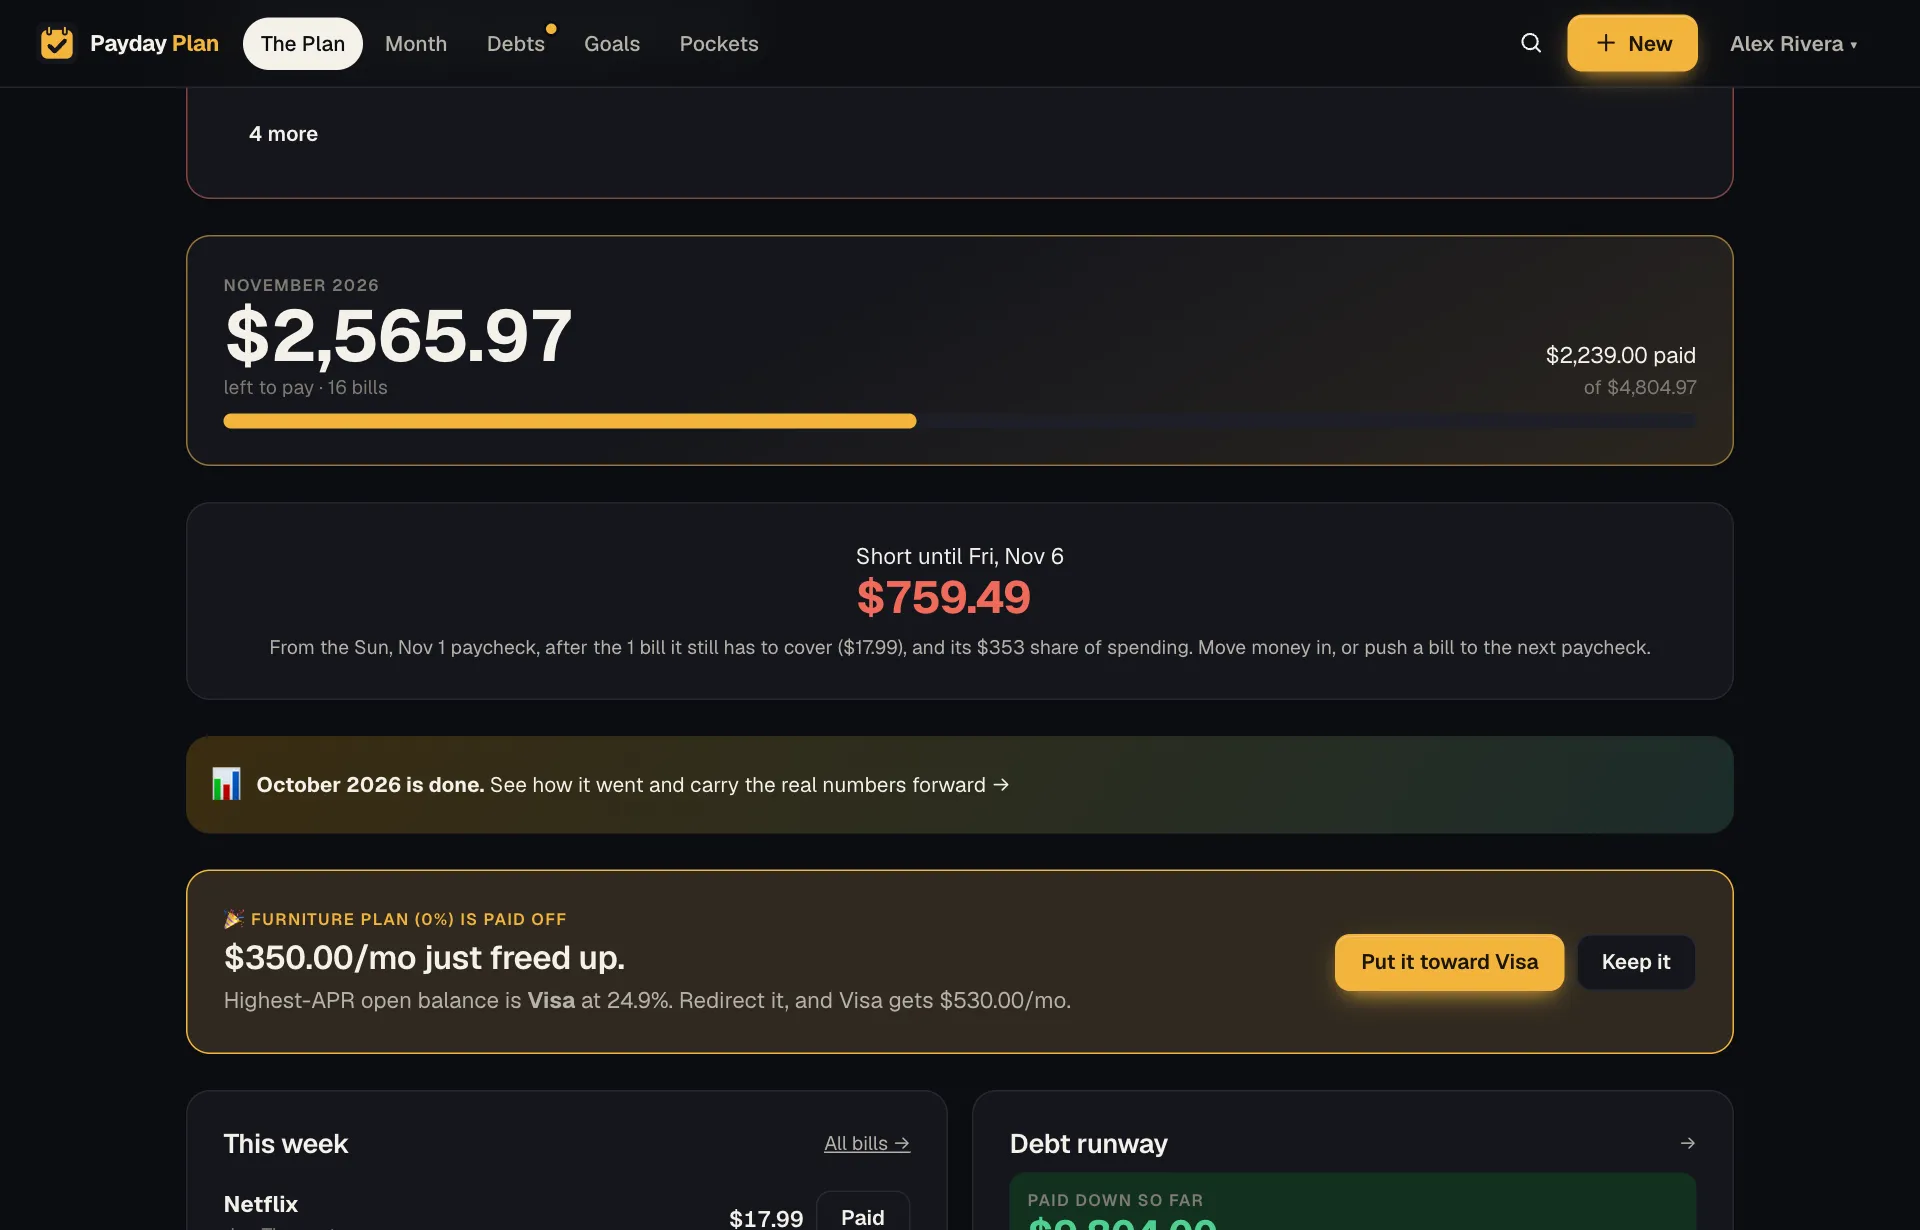
Free to spend = this paycheck − the bills it has to cover before the next payday − its share of everyday spending.
Three parts, each doing a specific job.
This paycheck. Not the balance. The balance mixes this paycheck with leftovers, money set aside for something else, and whatever the last paycheck was supposed to be holding for rent. Start from what came in.
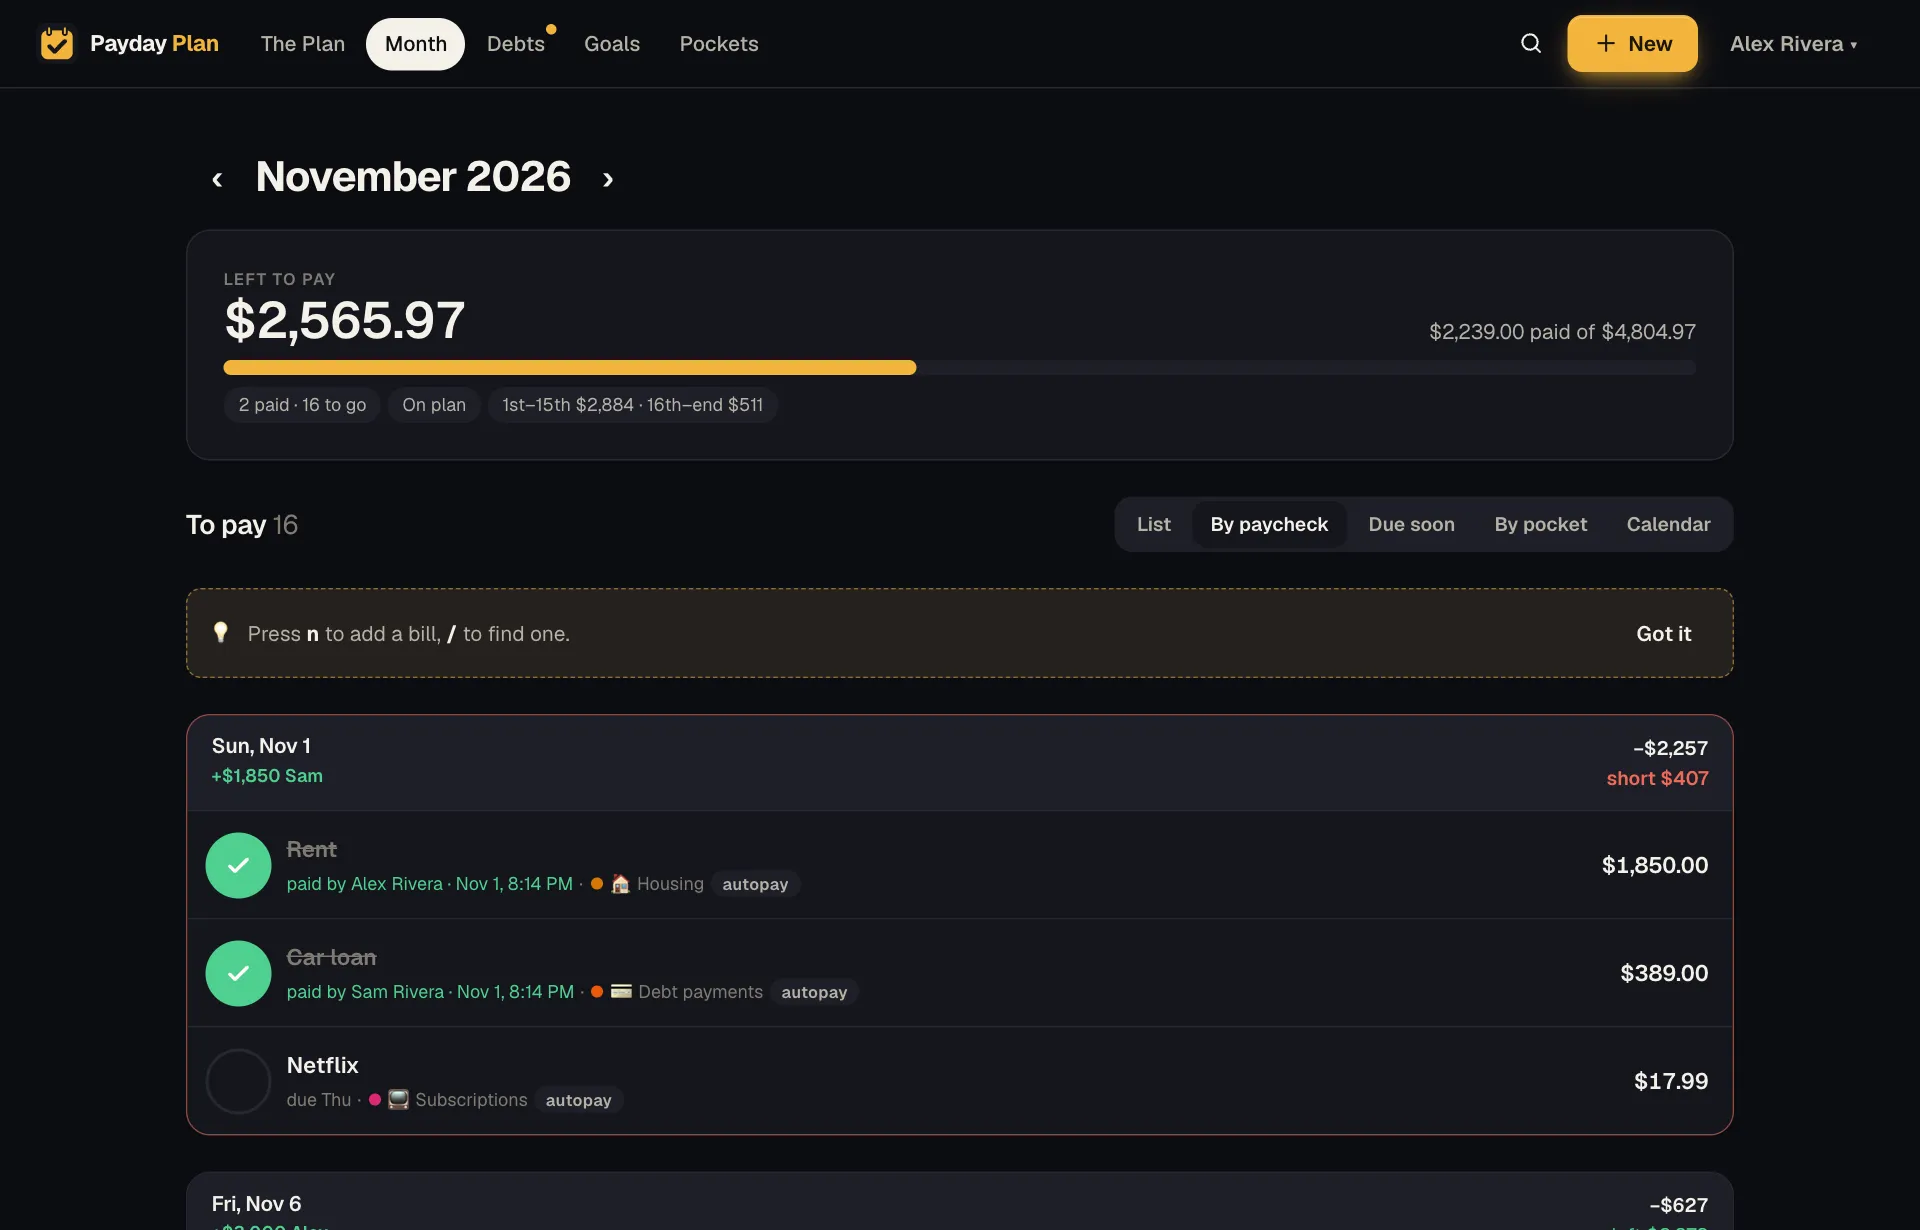
The bills it has to cover. Every bill due from today up to the day before your next payday. Not the whole month's bills, and not none of them. Just this window.
Its share of everyday spending. Groceries, gas, school lunches, the pharmacy. These aren't bills, but they aren't optional either. If you plan $1,400 a month for them and you're paid twice, each paycheck owes about $700.
What's left really is free. You can spend it on dinner out, put it toward a debt, or leave it alone, and nothing in the plan gets hurt.
A worked example
A made-up household, paid $3,000 every other Friday. Today is the 17th, payday. The next payday is the 31st.
| Amount | |
|---|---|
| This paycheck | $3,000 |
| Internet (18th) | −$80 |
| Credit card payment (21st) | −$300 |
| Childcare (26th) | −$1,100 |
| Streaming (28th) | −$45 |
| Share of everyday spending | −$700 |
| Automatic transfer to savings | −$150 |
| Free to spend until the 31st | $625 |
Notice what isn't there: rent. It's due on the 1st, and the paycheck on the 31st will be in the account by then, so it's that paycheck's job. Next month the Fridays shift and the rent may land on this paycheck instead. That's why the number gets worked out fresh every payday rather than once a year.
So: $625 for fourteen days, a little under $45 a day. Compare that with the $4,200 balance that started this. Same household, same evening, a very different decision about the restaurant.
What it isn't
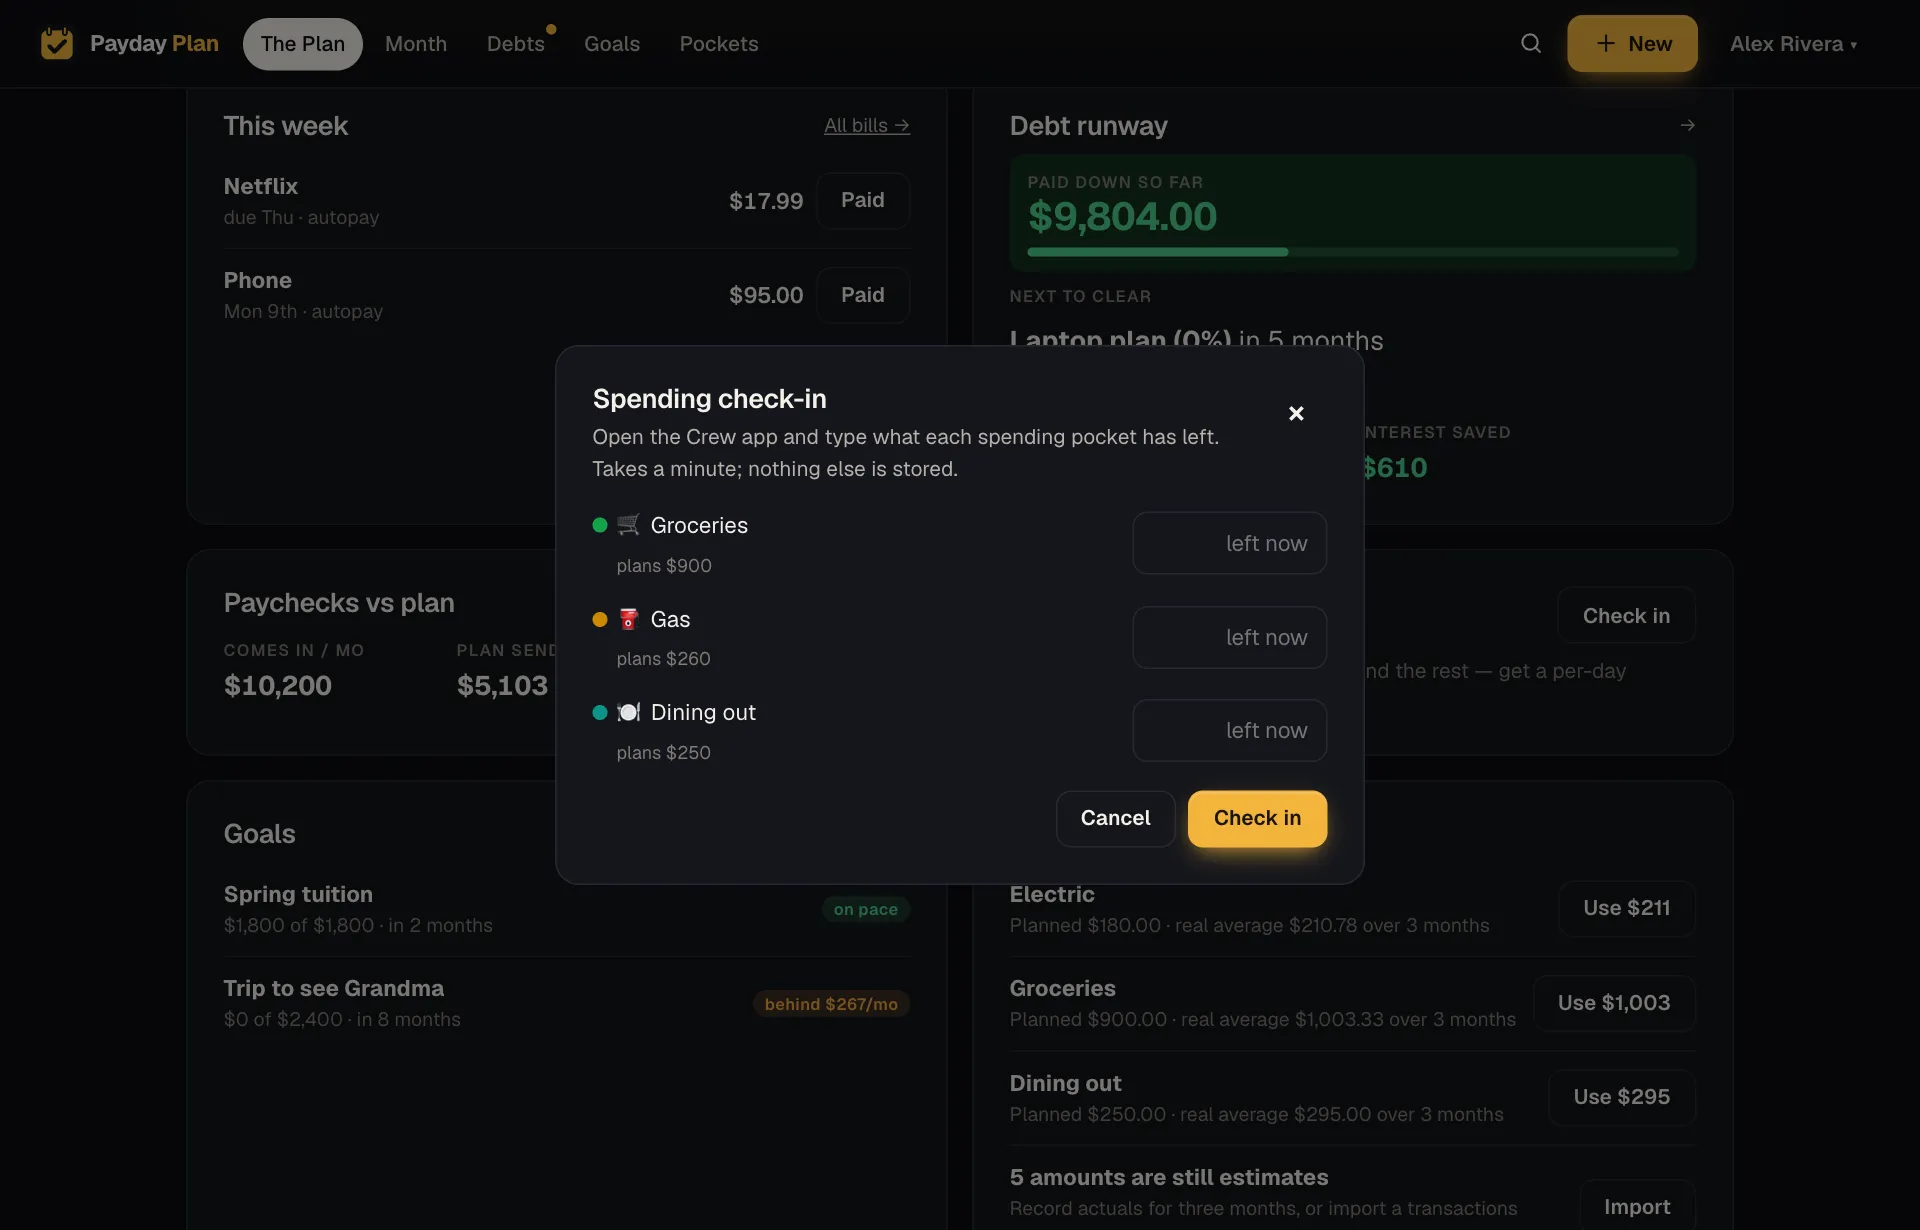
It isn't the grocery money. Groceries are already taken out. If you're running low on groceries, that's a separate problem with a separate fix: check what's left in that pocket and how many days it has to last.
It isn't savings. If you move money to savings every payday, treat that transfer like a bill so it comes off before you see the number. Money you only save "if there's some left" mostly isn't saved.
It isn't a target. A free-to-spend figure of $625 doesn't mean you should spend $625. It means you can without consequences. Some paychecks you'll want to spend less of it and send the rest somewhere useful.
When the number is small, or negative
A negative free-to-spend number is good news, oddly. It's telling you something true while there's still time to act.
Usually it means one of these:
- This paycheck carries a big bill. Rent, the mortgage, a quarterly insurance premium. Look at the paycheck before it: does it have room to set some aside? Moving a fixed amount from the long paycheck to the short one every time is the cleanest fix.
- An irregular cost landed in the window. Car registration, a school fee. Next time, that's a sinking fund, saved a little each month, so it doesn't land on one paycheck.
- The plan has stale estimates. If the electric bill is really $180 and the plan says $120, the number is optimistic every month. Replace the estimate with what actually came out.
- The plan is bigger than the income. If every paycheck is negative, it isn't a timing problem. Something has to come out of the plan.
Keep it honest during the fortnight
A free-to-spend figure is worked out on payday, but life keeps happening. Two habits keep it useful:
- Tick bills as they go out. If a bill came in higher than planned, record the real amount. The next calculation will be right.
- Check the spending pockets mid-way. If groceries are running ahead, you'll know before the free money gets spent covering them.